
TL;DR
India’s private markets have become excellent at raising capital. The next mark of maturity is how many credible ways that capital can come back to LPs, and the central theme of the ILPA roundtable was the role institutions will play in building those routes: the case for secondaries, the reservations, and what will bring institutional capital in.
- India’s IPO market is on a record run, and a mature market adds more exit doors alongside it: secondaries, continuation vehicles and strategic sales.
- Secondaries give LPs their own clock, letting them rebalance, recycle capital or meet obligations without waiting for a company to be IPO-ready.
- Global secondaries crossed $120B in H1 2026, the biggest half-year on record, and India now ranks second among emerging markets for GP-led deal volume.
- Domestic appetite is strong: over 98% of capital in Oister’s ACE secondaries funds comes from Indian investors.
Quick Answer
The LP clock is the idea that an LP’s need for liquidity should be independent of any single company’s exit timeline. Secondaries and continuation vehicles make that possible, giving LPs flexible, market-priced liquidity while great companies keep growing and list when they are ready.
What Is the LP Clock?
As India’s AIF ecosystem has matured, so has the LP conversation. AIF commitments reached ₹17.53 trillion as of June 2026, and LPs are now focused on DPI, exit visibility and when capital comes back.
India’s modern PE/VC industry began scaling around 2005–06, and many of its strongest companies are still growing as their funds reach the end of their terms. An LP may want to rebalance an allocation, recycle capital into new vintages or meet obligations to beneficiaries. A functioning secondary market separates the LP’s clock from the company’s: LPs gain liquidity on their own timeline, GPs hold winners longer, and companies list when they are ready.
A Mature Market Has Many Exit Doors
India’s IPO market is having a record run. Between April and September 2026, 78 companies raised ₹94,205 crore through mainboard IPOs, the most ever in the first half of a financial year. The goal is not fewer IPOs, but better-timed ones, supported by a broad set of exit routes.
Exit data shows that breadth is already building. In H1 2026, open-market sales made up 44% of PE/VC exit value and strategic sales another 36%. In July 2026, secondaries accounted for 52% of exit value.
| Exit share | India | Global |
|---|---|---|
| IPOs | About two-thirds of exits | — |
| Secondaries | Below 20% of exits | About one-third of exits |
That gap is India’s growth opportunity. As secondaries move toward global levels, LPs gain several doors open at once.
Continuation Vehicles: Liquidity Without Selling Winners
Globally, GP-led deals led by continuation funds reached $65B in H1 2026, up 35% year on year. Picture a fund in year eleven holding a few strong companies with another leg of growth ahead. A continuation vehicle lets LPs who want liquidity exit, while those who believe in the assets stay invested.
| Factor | Open-market sale | Continuation vehicle |
|---|---|---|
| Pricing | Fund-level discount | Priced on asset quality |
| LP choice | Sell only | Sell or roll |
| Strong assets | Exit with the fund | Keep compounding |
In H1 2026, LP interests in 10–12-year-old funds sold on the open market priced at a 22% discount to NAV. A continuation vehicle offers a better path:
Institutions and Secondaries: The Case For and the Considerations
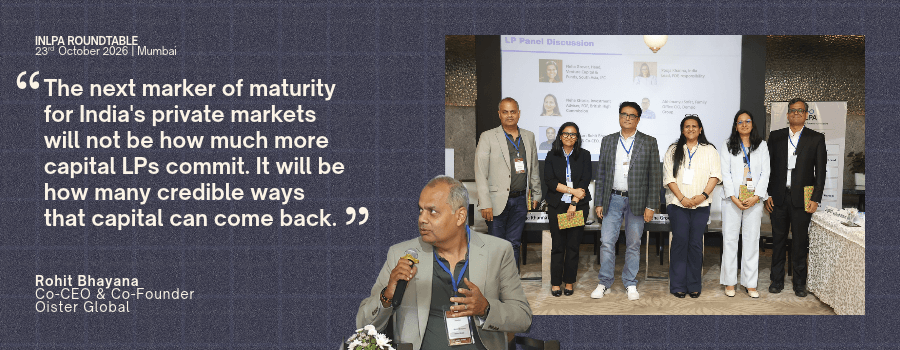
The ILPA roundtable, moderated by Rohit Bhayana of Oister Global with Neha Grover, Abhimanyu Sofat, Neha Khosla and Pooja Khanna, brought together perspectives ranging from a global DFI to a family office. The discussion centred on what makes secondaries attractive to institutions, what holds them back, and what will accelerate allocation.
| The case for secondaries | Institutional considerations |
|---|---|
| Shorter path to liquidity and DPI | Pricing: discounts are not automatic |
| Visibility into the portfolio | Conflicts of interest in GP-led deals |
| Quality assets at market prices | Mandate fit and allocation buckets |
| An independent check on NAVs | A newer category in India |
Each consideration has a clear answer emerging. On pricing, an EY study found 85% of Indian startup secondaries traded at par with concurrent primary rounds, a sign of the quality of assets changing hands. On governance, LPAC oversight, independent valuations and a real choice to sell or roll make continuation vehicles fair for every LP. Track records are building fund by fund, and dedicated allocation buckets and regulatory clarity will make secondaries a natural fit for institutional mandates.
The shared conclusion: secondaries and continuation vehicles solve a real liquidity need, they are here to stay, and institutions and LPACs should be part of them.
Indian LPs Are Building the Exit Door
Domestic LPs are backing secondaries with their capital. Oister’s last two secondary funds were oversubscribed, and the third is raising faster than either. Over 98% of the capital in Oister’s ACE secondaries funds has come from domestic investors, mostly family offices and HNIs.
LPs see secondaries in two ways: as access to mature private companies with shorter duration and clearer exit visibility, and as liquidity infrastructure for the rest of their private-market book. The same LPs who need an exit door are helping to build it.
The next wave of capital is ready to follow. India’s domestic institutions currently use just 7.5% of their available investment limits, leaving significant room for secondaries to become a core part of institutional portfolios.
The Next Step: Making Mid-Life Liquidity Routine
As the ecosystem matures, there is a strong opportunity to make mid-life liquidity easier. Clear, efficient frameworks for transfers of LP interests and continuation vehicles, with fair processes, independent pricing and real choice for LPs to sell or roll, will make ownership changes a routine part of an institutional market.
In a mature market, liquidity becomes a market of its own, where LPs can enter and leave at different stages on their own timelines.


 Call Us