
TL;DR
- India’s private markets have built a deep, high-quality capital base, and secondaries are now turning that value into cash for investors, founders and employees. This was the central theme of the IVCA panel “The Rise of India-Focused Secondary Funds: Strategies, Returns and Liquidity Infrastructure.”
- Secondaries have grown into a portfolio-rebalancing tool used by LPs, GPs and founders alike.
- The deal type follows who needs liquidity: LP-led deals, GP-led continuation vehicles, or direct secondaries.
- DPI is now the metric Indian LPs value most, and secondaries are one of the fastest routes to it.
- India’s secondaries market grew 32% in FY25 to $4.4B, and H1 FY26 alone reached $4.2B.
Quick Answer
The liquidity unlock is the shift in India’s private markets from waiting for IPOs to accessing liquidity continuously through secondaries. With $26–52B of supply expected over the next three to four years, secondaries are set to become a core pillar of the ecosystem, delivering DPI to LPs and real wealth to founders and employees.
Why Secondaries, Why Now
India’s private markets have scaled impressively. AIF commitments reached about $204B by June 2026, up 23.6% year on year, and 84% of Indian schemes have already made distributions. The next phase is about converting strong portfolio value into cash at scale, and secondaries are the engine for it.
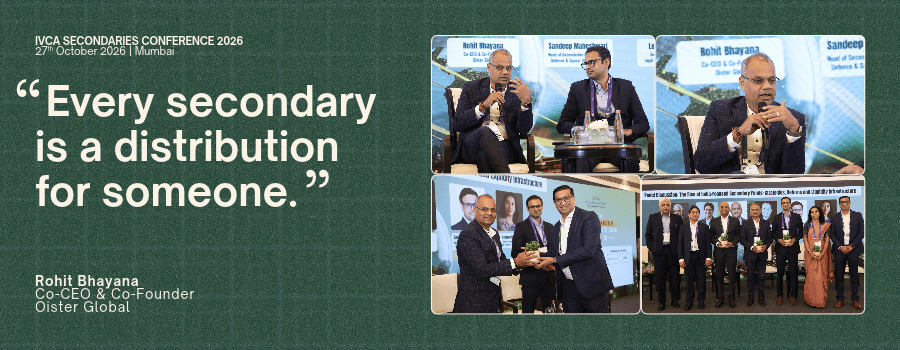
The IVCA panel brought together five secondaries specialists: Alok Gupta (Foundation PE), Nitin Agarwal (Neo Asset Management), Pranav Gupta (EastGate Secondaries), Rohit Bhayana (Oister Global) and Sandeep Maheshwari (360 ONE Asset).
Who Needs Liquidity Decides the Deal
As Rohit Bhayana, Co-CEO and Co-Founder of Oister Global, framed it, the right structure depends on one question: who needs liquidity?
| Who needs liquidity | Deal type | What it delivers |
|---|---|---|
| An LP wants to rebalance | LP-led secondary | Portfolio flexibility before fund maturity |
| A GP wants to keep a winner | GP-led continuation vehicle | More time to compound a strong asset |
| Early investors in a near-IPO company | Direct secondary | Liquidity ahead of listing |
GP-led deals are now the majority globally, showing that managers use secondaries to hold their best assets longer. In India, average deal size has grown 3.7x, from $0.03B in FY20 to $0.10B in H1 FY26, as the market becomes increasingly institutional.
DPI: The Metric LPs Value Most
DPI measures real cash returned to investors, and it now drives LP re-up decisions in India. Bhayana noted that the strongest managers pair DPI with three qualities: meaningful capital returned, distributions earned through genuine value realisation, and a high-quality portfolio that keeps growing.
Because every secondary is a distribution for someone, secondaries are a natural DPI engine. Oister built its fund around this idea, with a 5-year fund life and 3 of 6 companies in Fund I already reaching public-market outcomes.
Entry-Price Discipline
Strong secondary returns begin with disciplined entry. Bhayana outlined the approach:
- Price against listed peers, so valuations are anchored to live market data.
- Win on sourcing. A long-standing LP relationship with Indian VC funds brings first calls on negotiated deals.
- Stay selective, backing only opportunities that meet the bar.
- Glass-box transparency, with LPs seeing the pipeline before they commit.
In India, top-tier assets trade near par, while tail-end portfolios offer 30–40% discounts, giving disciplined buyers attractive entry points across the spectrum.
The Growth Story in Numbers
| Metric | Global | India |
|---|---|---|
| Annual secondaries volume | $240B (2025) | $4.4B (FY25) |
| Growth | 17% CAGR (2019–2025) | 32% (FY25 vs FY24) |
| Private capital as share of GDP | About 5% (peer economies) | About 1%, room to grow 5x |
| Supply pipeline (next 3–4 years) | — | $26–52B |
Sources: Jefferies, Barings, Praxis, Oister x Crisil.
The return profile is equally compelling. Secondaries have delivered a 15.4% five-year rolling IRR versus 7.5% for the MSCI ACWI, returned 9–15% through the 2008 crisis, and have the lowest loss rate of any private strategy, with only 1% of funds returning below 1x.
What to Watch: Continuous Liquidity
Liquidity is becoming continuous rather than a single end-of-fund event, and its impact reaches well beyond portfolios.
- Employees: Selling even 10% of ESOPs can mean ₹16 lakh for a wedding or a home, turning equity into real wealth.
- Founders: A small secondary lets a founder buy a house while staying fully focused on building the company.
- LPs: Regular secondary activity lets LPs rebalance and recycle capital with confidence.


 Call Us